HMO Finance for Houses in Multiple Occupation
Whole-of-Market Access
Our Lending Partners
We work across leading UK banks, building societies and specialist lenders to source finance suited to your goals.
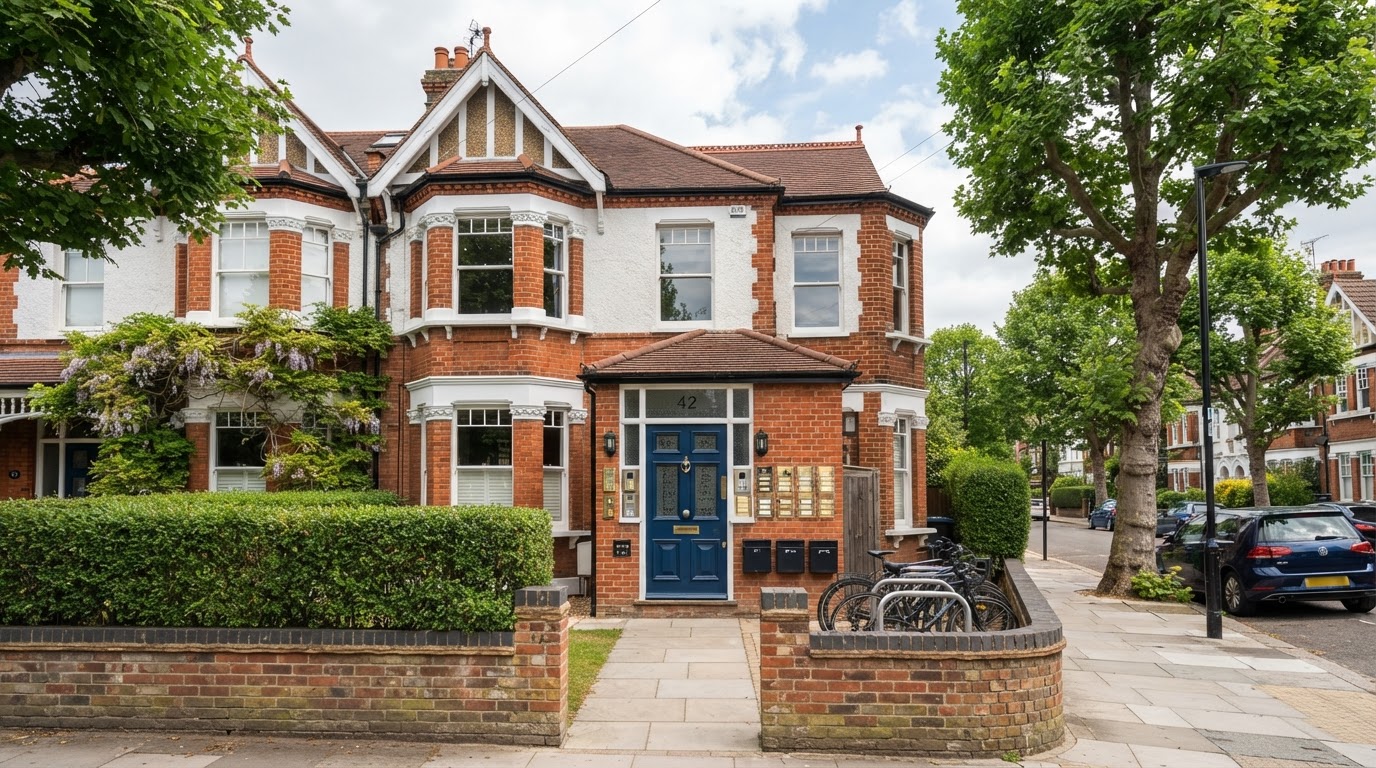
A house in multiple occupation (HMO) is a property let to several tenants who are not a single household, often with shared facilities. Lenders treat HMOs differently from standard buy-to-let property, and the options available can be more specialised. Hunter Capital helps landlords understand what may be available.
Who It May Be Suitable For
How It Works
Discuss the property
We talk through the property, how it is let and what you are trying to achieve.
Review the market
We look across the market for finance options suited to HMO property.
Prepare the application
We help gather the information lenders typically need for HMO cases.
Support to completion
We keep the application moving and help resolve queries as they arise.
What Hunter Capital Can Help With
- Explaining how HMO finance differs from standard buy-to-let
- Reviewing options across the market
- Supporting purchases and remortgages
- Helping you understand lender criteria
Key Considerations
- !Licensing requirements may apply to certain HMOs
- !Lenders may have specific criteria about the number of tenants or rooms
- !Some HMO finance is not regulated by the Financial Conduct Authority
- !Rental assessment may differ from a standard buy-to-let
Frequently Asked Questions
Whether a property is an HMO depends on factors such as the number of tenants, their relationship and whether facilities are shared. Licensing rules can also apply. We can talk through your situation, though you should confirm the legal position with the relevant local authority.
Yes. Lenders often treat HMOs as a specialist category with their own criteria. This is one reason it helps to review the market rather than approach a single lender.
Some HMO finance is not regulated by the Financial Conduct Authority. We will explain the regulatory position for any option we discuss.
Related Services
Speak to an Adviser About HMO Finance
Book a no-obligation consultation to discuss your circumstances and explore what may be possible.