Sharia-Compliant Mortgages & Islamic Finance in Oldham
Whole-of-Market Access
Our Lending Partners
We work across leading UK banks, building societies and specialist lenders to source finance suited to your goals.
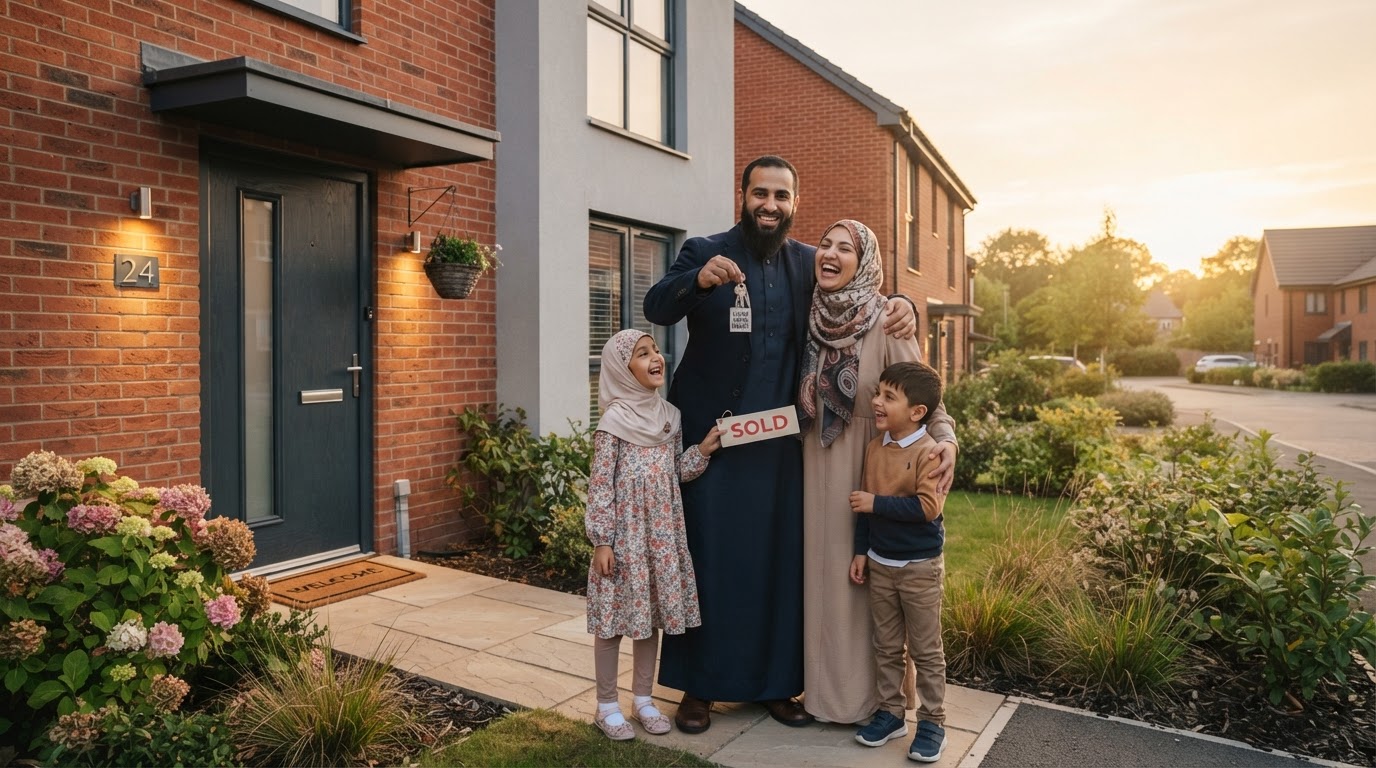
Sharia-compliant finance offers a way to buy a home or fund property and business without relying on interest, in keeping with Islamic principles. Instead of lending money at interest, providers use structures such as co-ownership or leasing. Based in Oldham, Hunter Capital helps individuals, families, first-time buyers and investors across Greater Manchester and the wider UK understand the halal finance options available and find an approach that fits both their faith and their circumstances.
Who It May Be Suitable For
How It Works
Understanding your situation
We start with a no-obligation conversation about what you are trying to achieve, your timescales and your preference for Sharia-compliant finance. There is no pressure to proceed.
Exploring the market
We look across the specialist Sharia lender market for options that may be suitable, rather than approaching a single provider, so you can see what is available.
Explaining the structure
Sharia-compliant finance works differently from a conventional mortgage. We explain how each option is structured — for example co-ownership or leasing — so you understand what you are entering into.
Supporting your application
When you are ready to move forward, we help prepare the application, deal with the provider on your behalf and stay involved through to completion.
Sharia-Compliant Finance Structures
Sharia finance uses a small number of established structures rather than interest-based lending. These are the main approaches you may come across.
Murabaha Finance
The provider purchases an asset and sells it to you at a markup agreed in advance. This creates a transparent, asset-backed structure without interest.
Common uses
Ijara (Islamic Leasing)
Works like leasing — you pay rent for an asset and may buy it at the end of the term. A flexible option for those who want to keep their choices open.
Common uses
Diminishing Musharaka
A partnership where both you and the provider contribute funds. Over time, you gradually buy out the provider's share until you own the asset completely.
Common uses
Who Benefits from Sharia Finance?
Our Islamic finance solutions serve a diverse range of clients seeking ethical financial options.
Muslims
Access modern financial services while living in line with Islamic principles and faith.
Ethical Investors
Non-Muslims who value transparent, ethical finance that avoids speculation and harmful industries.
Businesses
Companies seeking risk-sharing partnerships rather than debt-heavy financing models.
Investors
Those looking for diversification and access to asset-backed investment opportunities.
What Hunter Capital Can Help With
- Explaining how Sharia-compliant home finance works in plain English
- Comparing options across the specialist Sharia lender market
- Supporting home purchase and remortgage applications
- Helping you understand how halal finance differs from a conventional mortgage
- Guiding first-time buyers through the process step by step
- Reviewing options for investment property finance where available
Key Considerations
- !Sharia-compliant products use structures such as co-ownership or leasing rather than charging interest
- !The number of specialist providers is smaller than the conventional mortgage market
- !Some Sharia-compliant home finance products are regulated by the Financial Conduct Authority
- !Deposit requirements and eligibility criteria vary between providers
- !The structure of the finance can affect how the arrangement is treated for tax and legal purposes
- !As with any property finance, your home may be at risk if you do not keep up with payments
Frequently Asked Questions
A conventional mortgage involves borrowing money and paying interest. Sharia-compliant finance avoids interest by using alternative structures, such as the provider buying the property and you acquiring it from them over time, or leasing it from them. We explain exactly how each available option works so you can decide with confidence.
Some Sharia-compliant home finance products are regulated by the Financial Conduct Authority, while other forms of finance may not be. We will always explain the regulatory position for any option we discuss so you know where you stand.
Yes. Sharia-compliant finance can be an option for first-time buyers who want to purchase a home without relying on interest. We can talk through your deposit, your circumstances and what may be available to you.
Sharia-compliant options may be available for investment property as well as for a home you intend to live in. Availability depends on the provider and your circumstances, and we can review what may be possible.
Most Sharia-compliant home finance arrangements require a deposit, just as a conventional mortgage would. The amount you can put down can affect the options available, and we can help you understand what to expect.
The simplest first step is a no-obligation conversation. We will talk through your situation, explain how Sharia-compliant finance works and outline the options that may be available, so you can decide whether and how to move forward.
Sharia Finance Enquiry
Ready to Explore Your Options?
Get in touch with our Sharia finance specialists today. We'll guide you through the best options for your situation, ensuring full compliance with Islamic principles.
Related Services
Residential Mortgages
Guidance through the residential mortgage process for purchases, remortgages and moves across the UK.
Buy-to-Let Mortgages
Mortgage guidance for landlords purchasing or refinancing rental property.
Expat & Foreign National
Mortgage and finance guidance for UK expats and foreign national buyers.
Speak to an Adviser About Sharia Finance
Book a no-obligation consultation to discuss your circumstances and explore what may be possible.